The regional developer was left out of credit
Banks have become pricier and more selective, and the public fund has stopped growing. Tokenized capital can fill that space, as long as it comes with real backing, clear rules and a structure that does not strangle those who build.

The Radar Terracotta newsletter published a line that sums up the moment in real estate: production credit has doubled, but it does not reach the regional developer. The money exists. In practice, it stays with those who already have the size, the track record and the collateral to offer the bank.
And the picture has worsened in recent weeks. In the session after the 25 October runoff, the DI for January 2031 jumped from 12.64% to 15.19%. Bradesco raised its mortgage rates. And the FGTS housing budget stopped growing for the first time in six years. The two sources that hold the sector up, the bank and the public fund, are tightening at the same time.
The bank chooses, and the regional developer loses
It is not ill will on the bank's part. It is arithmetic. With long rates rising and fiscal uncertainty, the bank cuts risk. That means sticking with the large developer, with audited accounts and collateral to spare. The regional developer, who has good land, a good product and knows local demand better than anyone, goes to the back of the queue.
This happens just as selling has become harder. Cancellations reach 21% in the mid and high-end segments. RFM went as far as offering tennis lessons with Fernando Meligeni to close sales. Slow sales mean less of the developer's own money to keep the build going, and that is exactly when credit is missed most.
The risk that shows up after signing
A developer without credit tends to accept any funding. It is an expensive mistake. Terracotta showed how mandatory amortisation, collateral substitution and additional capital calls lock the developer in when sales slow. The money comes in, the build moves, and a few months later the contract becomes the project's biggest risk.
Good funding is not the cheapest on paper. It is the one still standing in the bad scenario. A bankrupt developer pays no one: not the bank, not the investor.
Where tokenization comes in, without the hype
Tokenization in Brazil passed R$ 10 billion in August, about ten times the volume of a year earlier. But 88% of that volume is private credit and receivables. Real estate is still a niche.
For those in the Web3 market, that figure says two things. The infrastructure is ready, and investors already accept tokenized assets. And real estate is the next frontier, not the current one. The space exists, but it has to be built with care.
The moment calls for care. The US$ 6.3 billion attack on Binance knocked confidence in crypto down once again. At the same time, the regulator is moving: the Central Bank's rule for virtual asset service providers has applied since 30 October, and the CVM created a pilot for tokenized securities. The message is clear. The market will reward those with real backing and clear rules, and punish those who sell promises.
Tokenizing property is not putting a building on the blockchain. It is splitting the funding of a real project into smaller parts, with registration, documentation and offering rules, and opening that project to an investor base the bank would never reach.
How we do it at Nimber
Nimber is a real estate investment platform registered with the CVM under Resolution 88. The model connects the developer who has a good project but no access to bank credit with investors who want exposure to property with real backing. The token is the digital record of a regulated offering, with a real development behind it. It is not a speculative bet.
We stand by two principles. First: the structure must not strangle the developer, because protecting those who build is the most direct way to protect those who invest. Second: transparency about risk. Instead of selling the projected return, the question that matters is the one Terracotta poses: how much has to go wrong before the investor loses capital?
Three questions a good offering answers
For the investor, and for any business owner looking at this market, a well-structured tokenized real estate offering answers three questions clearly:
1. How much has to go wrong before I lose capital? A good offering shows the bad scenario with the same transparency as the projected return.
2. What is behind the token? A real development, with a special purpose company, contracts and registrations. Technology is the means, and the property is the backing.
3. Does the structure work even when sales are slow? When the contract preserves the developer in the bad scenario, it also preserves the investor.
That is the standard we stand by at Nimber.
What remains
The regional developer was not left out of credit for lack of a project. It happened because the system concentrates. With long rates where they are, that will not change next quarter. Those who build outside the big centres will need another source of capital.
Tokenization can be that source, as long as it does the basics better than the traditional market: backing, rules and a structure that protects both sides.
If you are a developer and want to understand how to structure a raise, visit incorporadores.nimber.com.br.
If you are an investor and want to know the platform, visit nimber.com.br.
References
- 1. Radar Terracotta #204, 30/10/2026: market reaction to the runoff (DI Jan/2031 from 12.64% to 15.19%) and the headline "production credit doubles, but does not reach the regional developer".
- 2. Metro Quadrado, 29/10/2026: Bradesco raises mortgage rates.
- 3. Metro Quadrado, 03/11/2026: FGTS housing budget stops rising for the first time in six years.
- 4. Radar Terracotta #203, 23/10/2026: cancellations reach 21% in the mid and high-end segments; CVM creates a pilot for tokenized securities.
- 5. Metro Quadrado, 20/10/2026: RFM offers tennis lessons with Fernando Meligeni to close sales.
- 6. Radar Terracotta #202, 16/10/2026: contractual risks of funding (mandatory amortisation, collateral substitution, additional capital calls).
- 7. Brazil Tokenization Report 2026, Nexa Finance, cited in Radar TokenNation #13, 19/10/2026: tokenization above R$ 10 bn, 88% in private credit and receivables.
- 8. Radar TokenNation #11 and #13, 06 and 19/10/2026: Central Bank rules for virtual asset service providers, in effect from 30/10.
- 9. Startups, 03/11/2026: US$ 6.3 bn attack on Binance.
- 10. Radar Terracotta #200, 02/10/2026 (Investor Track): for the investor, what matters is the breaking point, not the projected return.
This article expresses the author's opinion and is not investment advice. Investments in crowdfunding offerings carry risks, including the total loss of the capital invested.
Michael Frigatti
View profileMore from the hub
See all news
The biggest hack in crypto history leaves a fundamental question: how prepared are we to respond to billion-dollar crises?
Before the stage, the table: PaytechLatam prepares a business gathering in São Paulo
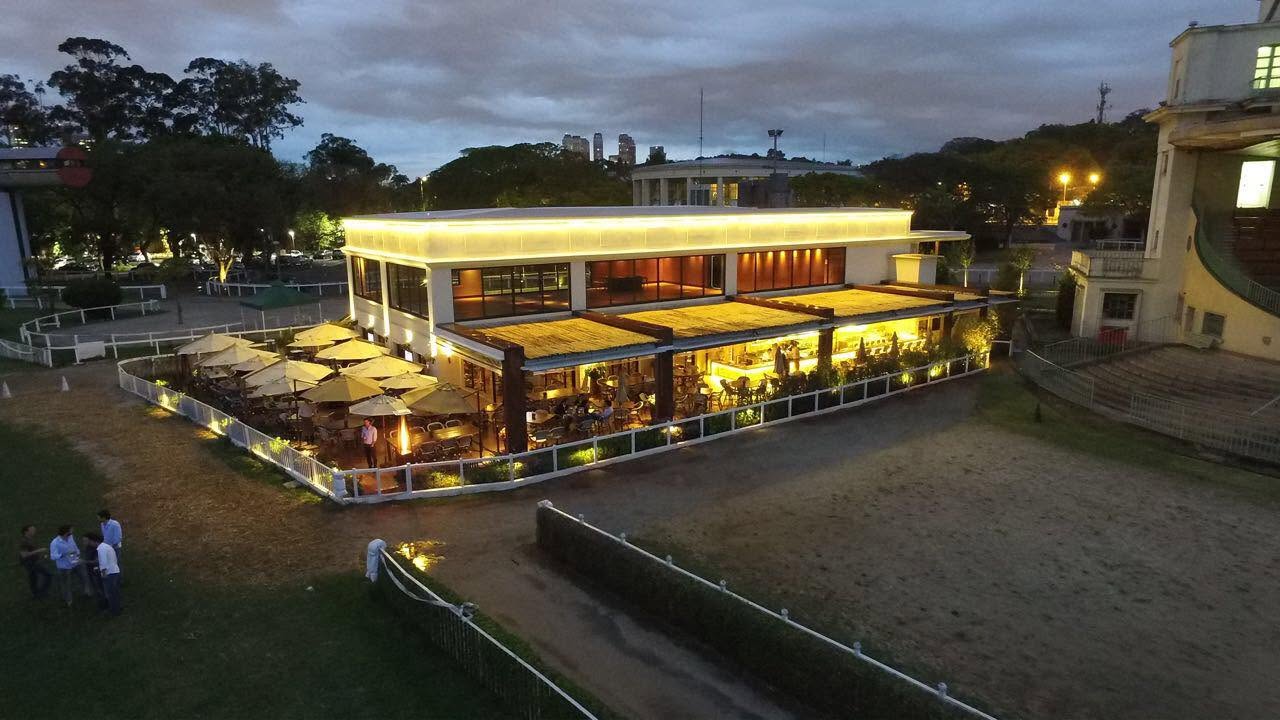
The PaytechLatam Executive Dinner brings together payments, open finance and fintech professionals for an executive dinner at the Jockey Club de São Paulo. The idea is to swap the traditional conference format for conversations at the table.